AdTech & MarTech
The Marketing Cloud Layer: Data, CDPs, and Integration
HubSpot, Salesforce, Adobe, Klaviyo, and Braze run the CDP layer under every AdTech stack. See what each vendor owns and why AI engines now bypass it.
HubSpot, Salesforce, Adobe, Klaviyo, and Braze run the CDP layer under every AdTech stack. See what each vendor owns and why AI engines now bypass it.
The owned-content infrastructure AI engines retrieve from for buyer queries. Built well, it substitutes for the top-of-funnel programmatic display spend brand teams have been compressing for a decade.
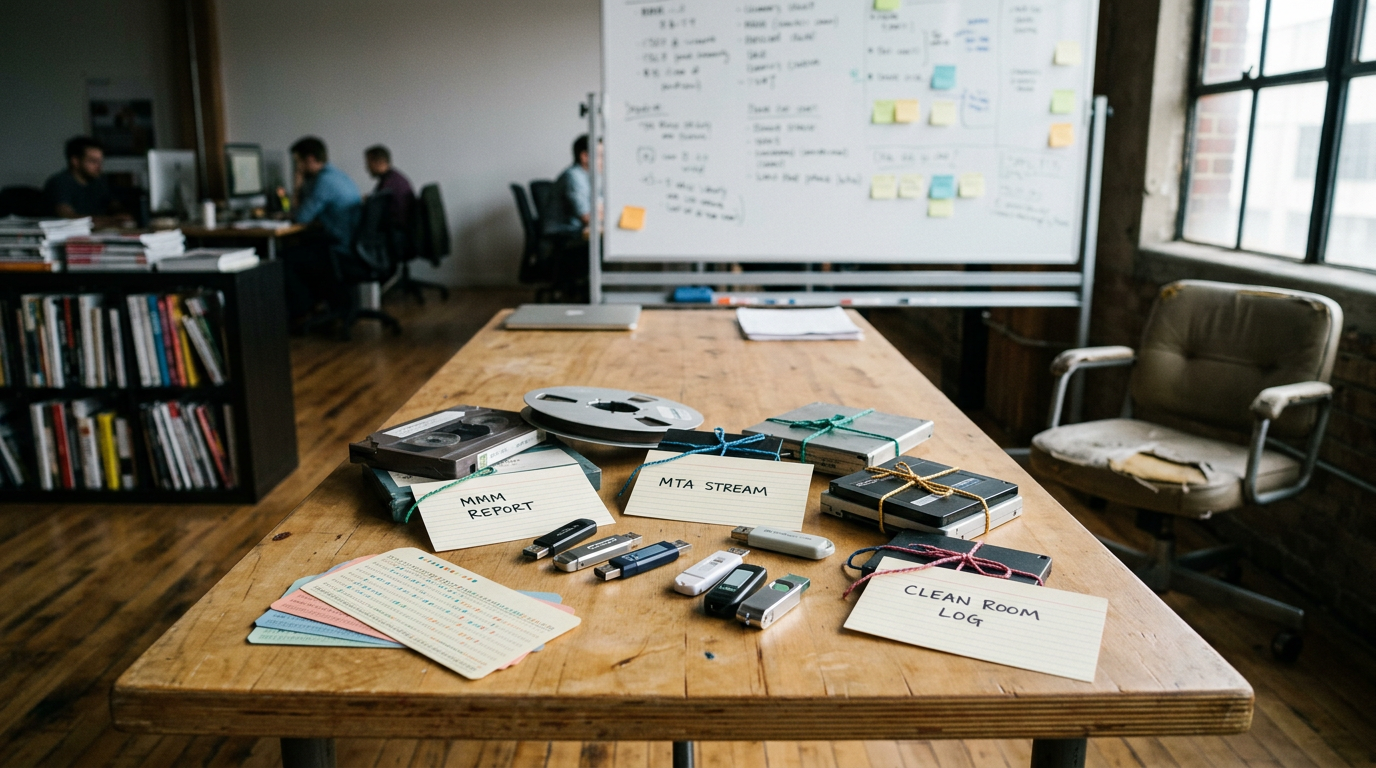
MMM, MTA, incrementality, clean rooms, walled-garden self-reporting. The single-source-of-truth measurement era is over. Here's how 2026 brand teams are managing the portfolio.
OpenAI Instant Checkout. Google Universal Commerce Protocol. Walmart as double anchor. The single shift that turns answer-engine visibility into a sales-channel revenue line.
Netflix Ads. Prime Video ad-supported by default. Disney, NBCU, Paramount, WBD. Roku, Samsung, LG, Vizio. The 2026 CTV inventory map and what brand buyers need to know.
Amazon, Walmart, Kroger, Uber, Target, Instacart, DoorDash, Costco. The fastest-growing major ad category in U.S. history — who runs it and what brand teams need to know.
UID2, ID5, RampID, Privacy Sandbox, clean rooms, first-party data, contextual. The 2026 identity stack is a portfolio — no single ID replaced the cookie.
Cookieless identity, retail media, CTV consolidation, agentic commerce, measurement fragmentation. EPR's defended reference on the modern AdTech and MarTech stack.
DoubleVerify did $657M in 2024. IAS did $530M. The AI-driven brand-safety models they sell are systematically mis-classifying the creators who shape consumer purchase decisions — and the same bias shapes AI engine citation. The new measurement layer replacing them.
AdTech & MarTech PR: cookie deprecation, retail media (Amazon, Walmart, Target), AI in creative and buying. The discipline for the always-transition category.